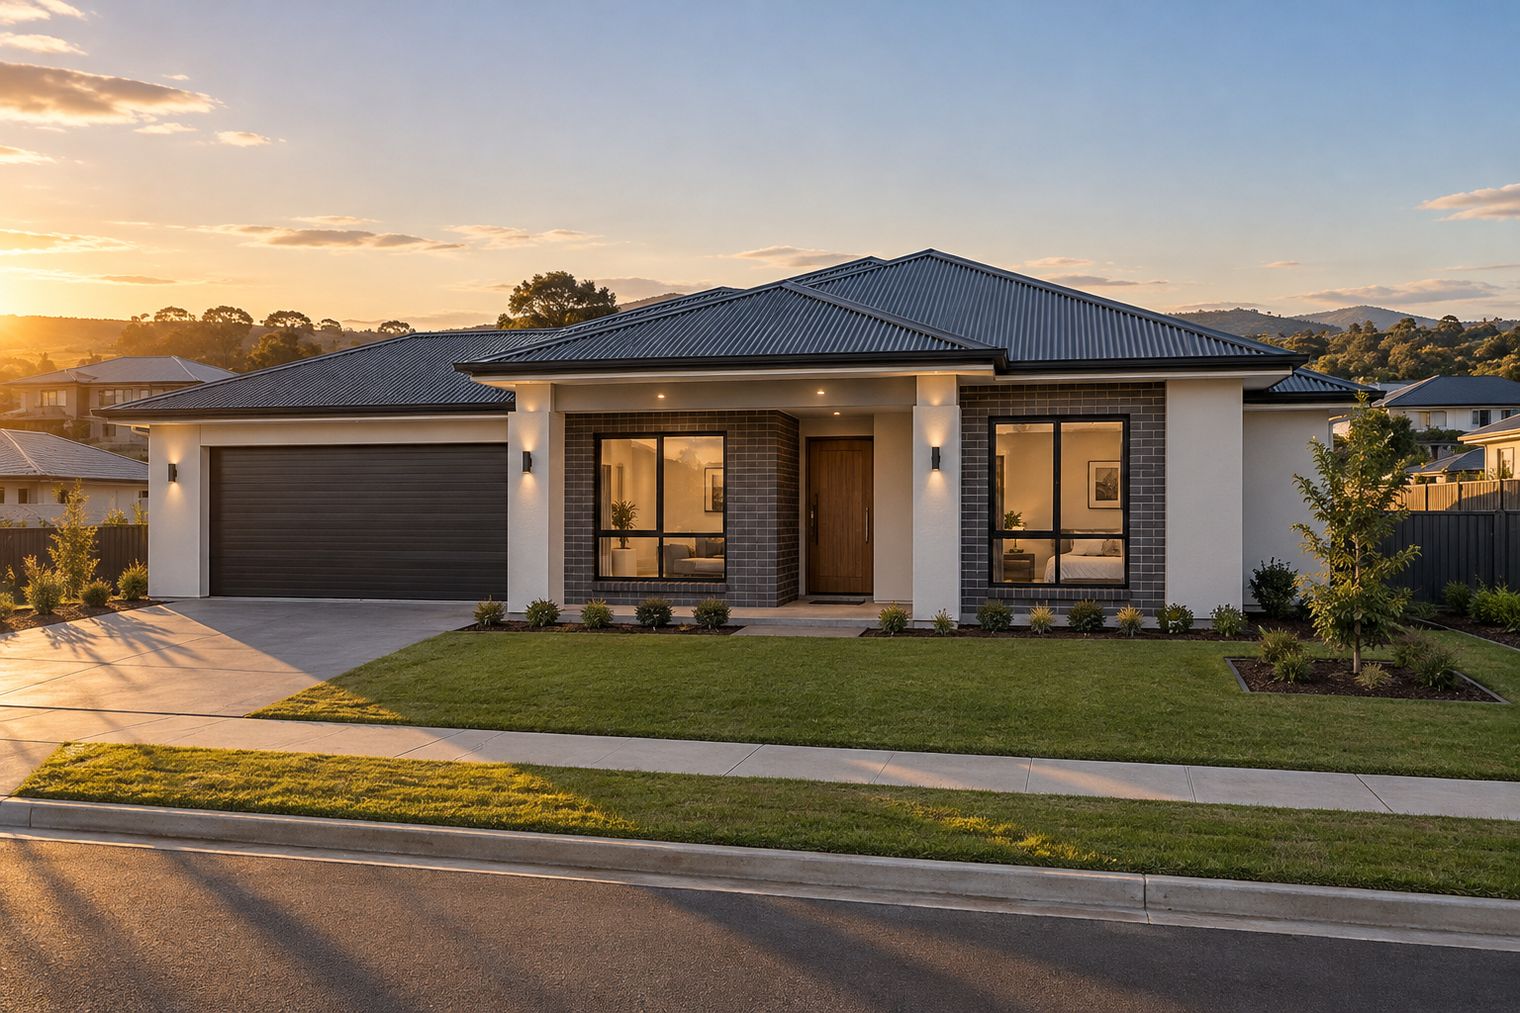
Most people who look at a house in a regional NSW town start with two numbers: the price and the weekly rent. The figures that decide whether the purchase works sit underneath those two, in stamp duty, the deposit, the loan, the tax rules and the weeks when the home is empty. This article uses one completed listing in Windradyne, a four bedroom, two bathroom, two car home at $875,000, to show how those pieces fit together.
The upfront costs before the first rent cheque
NSW transfer duty is the cost buyers most often underestimate, because it is paid on top of the deposit. The Revenue NSW table lists a band of $387,001 to $1,290,000 at $11,602 plus $4.50 for every $100 over $387,000. Applied to $875,000, that comes to about $33,562. That is my own calculation from the published bands, not a figure in the listing, so confirm it with Revenue NSW or your conveyancer before relying on it.
The first home buyer concession does not help here. It applies to eligible first home buyers, who pay no transfer duty on a new or existing home valued at $800,000 or less. This purchase is an investment, so it sits outside that concession.
Deposit is the second piece. Normally, borrowing more than 80% of a property's value means paying lenders mortgage insurance, a premium that protects the lender, not you. The listing says the home is available with a zero deposit. That would mean the loan covers the price, while duty and other purchase costs are met from elsewhere. Loan terms sit with a licensed broker. EWC is a property firm, refers loan enquiries to its broker network, and takes no commission on any loan. The government's First Home Guarantee is a different matter: it requires the property to be your primary place of residence, so investment purchases are excluded.
The rent figure and the upfront costs tell you more about this purchase than the headline price does.
Negative gearing, depreciation and the 2027 rules
Negative gearing lets an owner offset a net rental loss against other income. Several accounting summaries describe the 2026 reforms as ending that access for future investors in established homes from 1 July 2027, unless they buy a new build. Residential properties purchased before Budget night on 12 May 2026 have been grandfathered. Reports differ on how far the legislation has progressed, so check the current position with a tax adviser.
Whether a completed house counts as a new build matters a great deal. Early commentary treats a brand-new dwelling sold for the first time as the likely qualifier, though further Treasury and ATO guidance is still expected. Ask the question directly rather than assume the answer. New SMSF borrowing arrangements for residential property will no longer be permitted under the same reforms. An SMSF buyer needs an SMSF specialist before any other step.
Depreciation on the building is a separate item. Owners can claim a slice of the building cost each year, and the rate of deduction is generally 2.5% per year for 40 years following construction. The listing does not give a construction cost, so no deduction figure can be worked out from it. The build cost needs documentation, and a report from a qualified professional is one way to provide it. Amounts you do not claim still feed into the capital gain or loss calculation at sale.
When this suits and when it does not
A newer home in a regional town can suit a buyer who has savings beyond the deposit, can carry some months without rent, and values a 7-star energy rating. The listing rates the home 7 stars, which may help running costs compared with older stock, though the listing does not quantify that. Ask for the certificate.
It does not suit a buyer who needs rent to cover every cost from day one. It also does not suit anyone who has not worked out the loan structure, the cash needed at settlement, and how the 2027 rules would affect their own tax position. The listing cites a vacancy figure of about 0.67% from HtAG Analytics. A single low figure is a starting point, so ask for the date and method behind it. Published gross yields quoted in the listing range from 4.14% to 4.58%, and the rent assumption behind those yields deserves a close look.
Worked example: the numbers in this listing
The listing gives a price of $875,000 and an indicative rent of $600 a week for the whole property. That is $31,200 a year before any costs. Divided by the price, the gross yield at that rent is about 3.57%, which sits below the 4.14% to 4.58% range quoted in the listing. At this price, that range corresponds to roughly $697 to $771 a week, so an independent rental appraisal matters before anyone relies on either figure.
For a 20% deposit, the illustration uses $175,000, leaving a $700,000 loan before costs. Add the estimated duty of $33,562 and the cash needed reaches about $208,562, before legal, inspection and other settlement costs. Each 1 percentage point of interest on a $700,000 loan adds $7,000 a year, whatever the rate turns out to be. Each week the home sits empty costs $600 of indicative rent. At the 0.67% vacancy figure cited in the listing, the average loss would be about $209 a year.
The listing does not include rates, insurance, property management, maintenance or other holding costs, so no net cash flow can be calculated from it. The listing also cites house values up 45% over five years (OnTheHouse), and that is past movement, not a forecast. It places Bathurst railway station about 3.9 km from the suburb, which is worth checking on a map.
What to do next
- Ask an SMSF specialist accountant or a tax adviser how the 2027 negative gearing rules, the new build question and depreciation apply to your own situation.
- Talk to a licensed mortgage broker about loan options, including whether a zero deposit structure fits your numbers and what mortgage insurance and duty mean for cash needed at settlement.
- Get an independent rental appraisal and a quantity surveyor's estimate before committing. If you want to see current properties and request their details, visit current properties (request the details).
If you would like to talk through how these numbers apply to your position, book a free call with the EWC team.
General information only, not personal financial advice. Speak with a licensed adviser before acting.