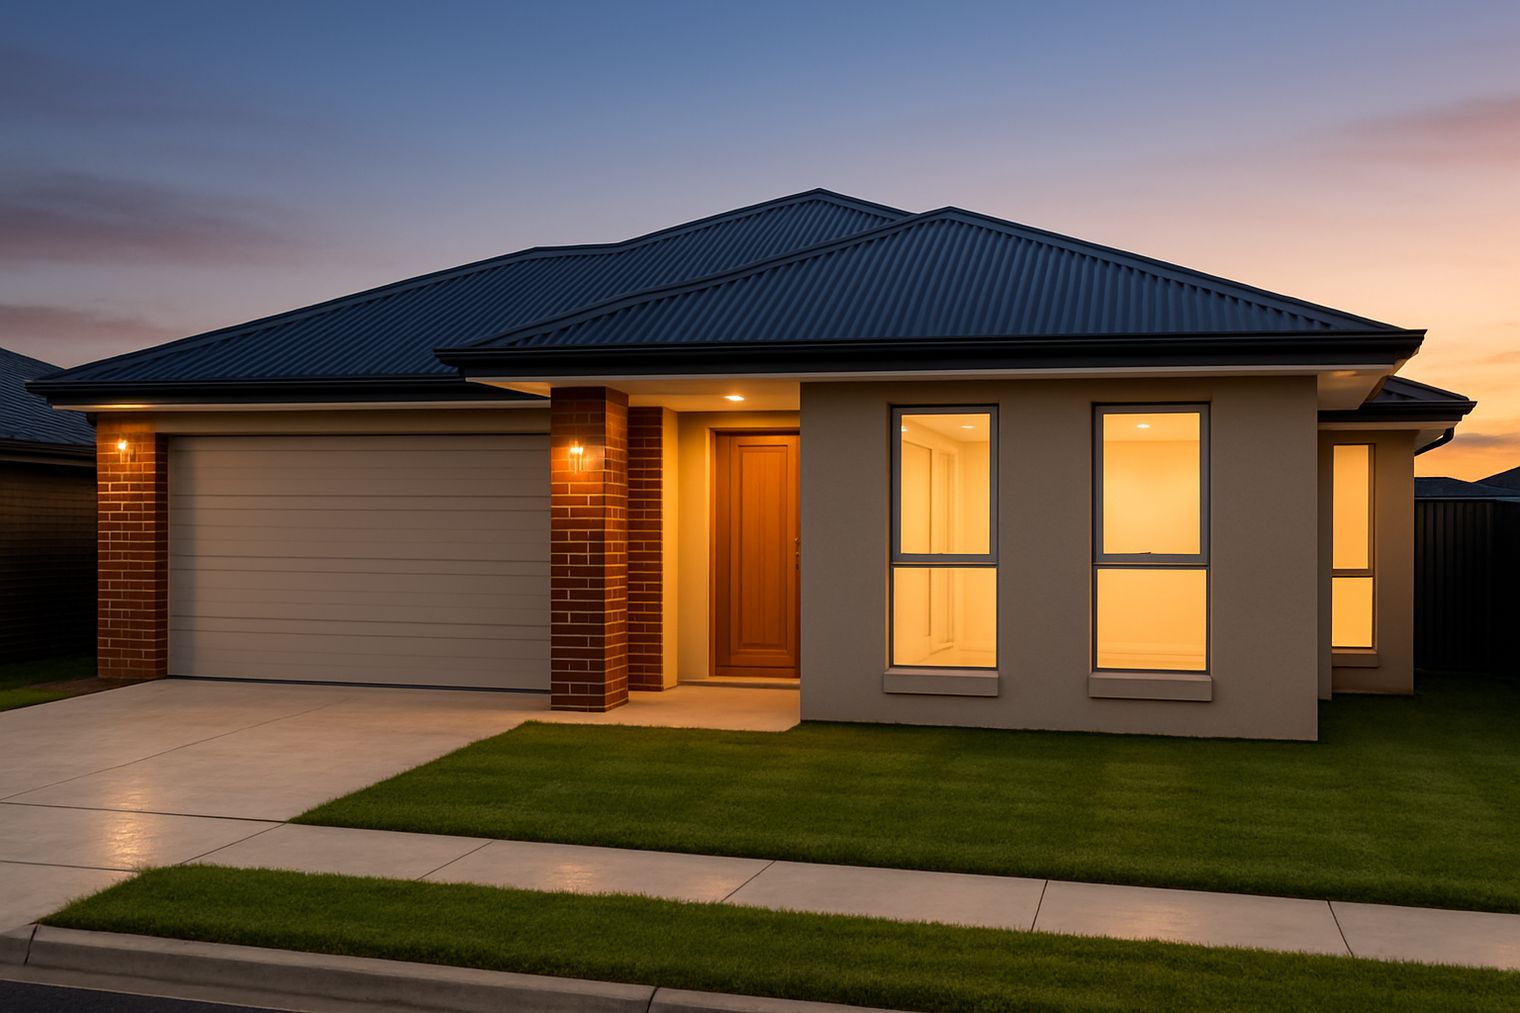
You have been watching the headlines about negative gearing reform and wondering whether the maths still works on an investment property. The short answer depends almost entirely on one question: are you buying a new build or an established home?
The distinction is now written into law, and it changes the comparison between the two asset types significantly.
What the 2026 Budget actually did
The Federal Budget handed down on 12 May 2026 introduced two connected changes affecting residential property investors.
First, on negative gearing: the changes limit negative gearing on established residential properties acquired after 7:30 pm (AEST) on 12 May 2026 (being contract date) by removing the ability to deduct net rental losses against income that is not rental income or gains from rental property. In plain terms, if you buy an existing house or apartment after that cut-off, any rental loss you make can no longer reduce your salary or wages bill. Excess rental losses may be carried forward to future years, but the immediate annual tax offset against your pay cheque is gone.
Second, on the CGT discount: the 2026-27 Budget removes the current 50% CGT discount, which will be replaced with cost base indexation and a 30% minimum tax on net capital gains from 1 July 2027. Transitional arrangements limit changes to gains arising on or after 1 July 2027, while prior gains remain subject to the current CGT discount.
Both changes apply from 1 July 2027. Properties held at Budget night are grandfathered in full.
The new build exemption in detail
Eligible new build residential properties remain exempt from these changes. For these properties, both negative gearing and the existing capital gains tax discount of 50% will still be available.
What counts as a new build? A new build is defined to include dwellings constructed on previously vacant land and dwellings created where existing properties are demolished and replaced with a greater number of dwellings. In general, off-the-plan apartments, house-and-land packages built on vacant land, and duplex developments that increase dwelling numbers are among the property types most likely to remain eligible under the proposed rules.
What does not qualify? Knock-down rebuilds or substantial renovations that do not increase supply will not be eligible. Substantial renovations alone would not convert an established property into an eligible new build under the proposed rules. Even large renovation projects would still generally be treated as established housing. Occupancy history also matters: a developer who builds and lives in an apartment before selling it to an investor may cause that property to be treated as established rather than new, so confirming eligibility with a registered tax adviser before signing a contract is important.
One further carve-out worth knowing: properties in widely held trusts and superannuation funds will be exempt from these changes, in addition to targeted exemptions for build-to-rent developments and private investors supporting Government Housing programs.
The trade-offs worth thinking through
The new build exemption is not an automatic advantage in every situation. There are real factors to weigh.
On the income side: A new build may carry a period of lower or no rental income during construction. Any rental income it does earn should be assessed on the basis of an independent rental appraisal, not developer estimates. Vacancy periods and body corporate fees (for apartments) affect real-world cash flow.
On the CGT side: For purchases of new builds, access to negative gearing will still be available, with an option to apply either the 50% CGT discount or the concurrently announced indexation and minimum 30% tax upon sale. Whether the 50% discount or the new indexed cost base produces a better outcome at sale will depend on your holding period, the rate of inflation, and your marginal tax rate at the time. That is a calculation for a qualified tax adviser, not a rule of thumb.
On the established property side: Losses on established properties bought after Budget night are not lost permanently in all cases. It appears that any losses incurred from an established residential property will be able to be offset against net rental income derived from other properties, including capital gains. As a result, a taxpayer's residential property income will be assessed on an aggregate basis for each income year, rather than losses being quarantined to a specific property. For investors already holding a portfolio, the interaction of old and new rules across multiple properties is worth mapping out carefully.
On depreciation: New builds typically offer stronger depreciation claims on plant and equipment and capital works under Division 43. That is a separate benefit, independent of the negative gearing rules, and one to discuss with a quantity surveyor and accountant.
A worked example (illustrative only)
Consider two investors, both on a marginal tax rate of 37%, both buying in the 2026-27 financial year.
- Investor A buys an established house for $850,000. The rental income is $36,000 a year and costs (interest, rates, insurance, maintenance) total $52,000. The $16,000 net loss cannot offset wages from 1 July 2027 onward. It carries forward.
- Investor B buys a new house-and-land package for $750,000. The same $16,000 net loss can still offset wages from 1 July 2027 onward, reducing taxable income by $16,000 and producing a tax saving of around $5,920 in the year it is claimed.
These figures are illustrative only, not a forecast of any property's costs or income. Actual figures depend on the specific property, finance structure, holding costs, and personal tax position.
At the CGT end, if Investor B sells after holding for more than 12 months, they can elect the 50% discount on the gain accrued after 1 July 2027, or the indexed cost base plus minimum 30% tax, whichever produces the lower liability. That election is made at the time of sale, not at purchase.
What to look at next
If you are weighing new builds against established property in light of these changes, three practical steps are worth taking now:
- Get the property classification confirmed in writing. Before exchanging contracts on any property sold as a new build, ask the developer or your solicitor to confirm it meets the ATO's definition as set out under the Treasury Laws Amendment (Tax Reform No. 1) Act 2026. A SMSF specialist accountant or registered tax agent can verify eligibility independently.
- Model the full cash flow picture with a licensed broker and accountant. The negative gearing saving is one part of the return equation. Borrowing costs, vacancy risk, strata levies, depreciation schedules, and land tax all affect real-world performance. Each factor should be stress-tested, not assumed.
- Consider how the SMSF exemption fits your situation. If property inside a self-managed super fund is something you are exploring, the negative gearing reforms do not apply to SMSF-held property. The tax treatment inside super is governed by different rules, and the structure used to hold the property matters significantly following regulatory changes in 2026. Speak with an SMSF specialist accountant before drawing any conclusions.
To understand how EWC sources and coordinates new build investment properties, including options for SMSF structures and construction finance, visit our services page or book a call. For more on how the 2026 reforms interact with super and SMSF property structures, browse our insights.
General information only, not personal financial advice. Speak with a licensed adviser before acting.